Find a local office


Future of BioLNG: Europe 2027
Be part of the Future of BioLNG: Europe 2027, hosted by ACI on the 24th & 25th March in Stockholm, Sweden. Bringing together the complete BioLNG value chain, this two-day conference will explore how Europe can turn its available BioLNG potential into bankable production and consistent customer demand.
As the market moves towards its next stage of development, discussions will address the commercial and regulatory conditions needed to accelerate scale-up. Key themes will include regulatory certainty, certification and mass balance, investment and project bankability, cross-border trade, infrastructure utilisation, production innovation and the expansion of demand across heavy-duty road transport, maritime and other downstream markets.
Building on last year’s edition with over 100 senior-level atttendees including Shell, Titan Clean Fuels, Gasum, TotalEnergies, Volvo and IVECO, Future of BioLNG Europe 2027 will connect producers, project developers, energy majors, traders, infrastructure operators, investors, policymakers and transport end users to tackle the practical barriers to growth and identify where the strongest opportunities lie.
What to Expect:
- Expert-Led Conversations: Participate in in-depth dialogues with policymakers and industry leaders on BioLNG policy frameworks, market dynamics, and pathways to decarbonization.
- Cutting-Edge Innovations: Explore breakthroughs in BioLNG production, including emerging techniques and the role of carbon capture and storage integration.
- Real-World Use Cases: Gain insights into how BioLNG is being implemented in the maritime and transportation industries, along with the practical challenges and advantages of its use.
- Pathways to Sustainability: Delve into solutions for securing sustainable feedstock sources and addressing logistical hurdles to scale BioLNG infrastructure.
- Global Networking: Build valuable connections with international policymakers, investors, industry pioneers, and stakeholders to drive future collaboration and investment
Key Themes:
- Regulation into Commercial Opportunity: Understand how evolving EU and national frameworks can provide greater certainty, support investment and create stronger conditions for BioLNG growth.
- Building Bankable BioLNG Projects: Explore the commercial models, long-term demand signals and investment conditions needed to develop viable projects beyond 2030.
- Trusted and Scalable Markets: Examine certification, mass balance, virtual liquefaction and cross-border trade to improve market transparency and unlock BioLNG supply across Europe.
- Growing Downstream Demand: Hear directly from the road transport and maritime sectors on what customers need to accelerate adoption and increase long-term BioLNG demand
Connecting the Complete Value Chain, on the 24th & 25th March in Stockholm: Meet BioLNG producers, developers, energy companies, traders, infrastructure operators, investors, policymakers, shipping companies, fleet operators and technology providers to develop the partnerships at the Future of BioLNG: Europe 2027.
For further details, please contact [email protected]
- Details
- Site Visit to ST1 Biokraft's BioLNG Facility
- Key Topics
- Who Will Attend?
- Confirmed Speakers
- Previous Edition 2026
- Sponsors
- Conference Agenda
- Maximising Face-To-Face Networking
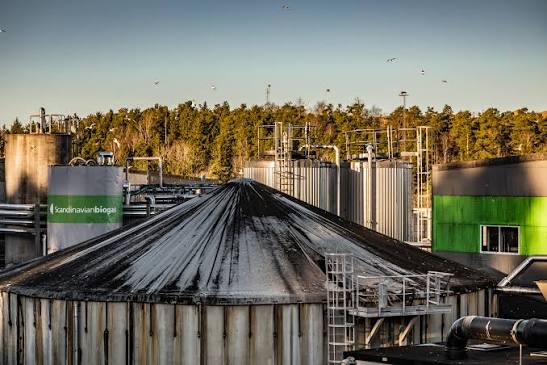
For up to 30 attendees on Tuesday 23rd March, ACI has organised a visit to ST1 Biokraft’s Liquefaction plant: In Södertörn, the original biomethane plant now has increased gas production capacity and a BioLNG liquefaction plant. It will be capable of producing both compressed biogas (CBG) and liquid biogas (Bio-LNG)
- Positioning BioLNG for Strategic Advantage in Europe’s Fuel Transition
- Managing Policy Risk Across BioLNG’s Long-Term Growth Horizon
- Protecting Returns and Unlocking Capital for BioLNG Growth
- Scaling Cross-Border BioLNG Trade with Trusted Market Infrastructure
- Converting Europe’s BioLNG Supply Pipeline into Secured Demand
- Maximising Returns from Europe’s Existing BioLNG Infrastructure
- De-Risking Scale-Up Through Commissioning and Operating Evidence
- Accelerating Commercial Adoption of BioLNG in European Fleets
- Monetising BioLNG Through Maritime Compliance and Customer Demand
- Diversifying BioLNG Revenue While Strengthening European Resilience
- Current & prospective BioLNG producers and distributors
- Liquefaction technology providers
- Biogas & Biomethane feedstock suppliers
- Truck manufacturers
- Road haulage fleet owners
- Ship owners
- Bio-based feedstock suppliers
- Government officials, regulators, and policymakers
- Financial stakeholders & investors
- Academia and research institutions
- Sustainability and chemical consultants
- Consultancy firms
- Engineering firms
- David Christopherson, Technical Sustainability Lead, Future Biogas
- Anna Lövsén, Head of Development – Biogas, Tekniska Verken Group
- Stephane Roelly, Portfolio Manager – Renewables, Gasum
- Jan Schubert, Commercial Director – LNG Bunkering, Avenir LNG
- Markus Olsson, Biomethane Business Development Director, Flogas
- Tünde Köteles, Value Chain and Project Management Expert, MOL Group
Event Overview
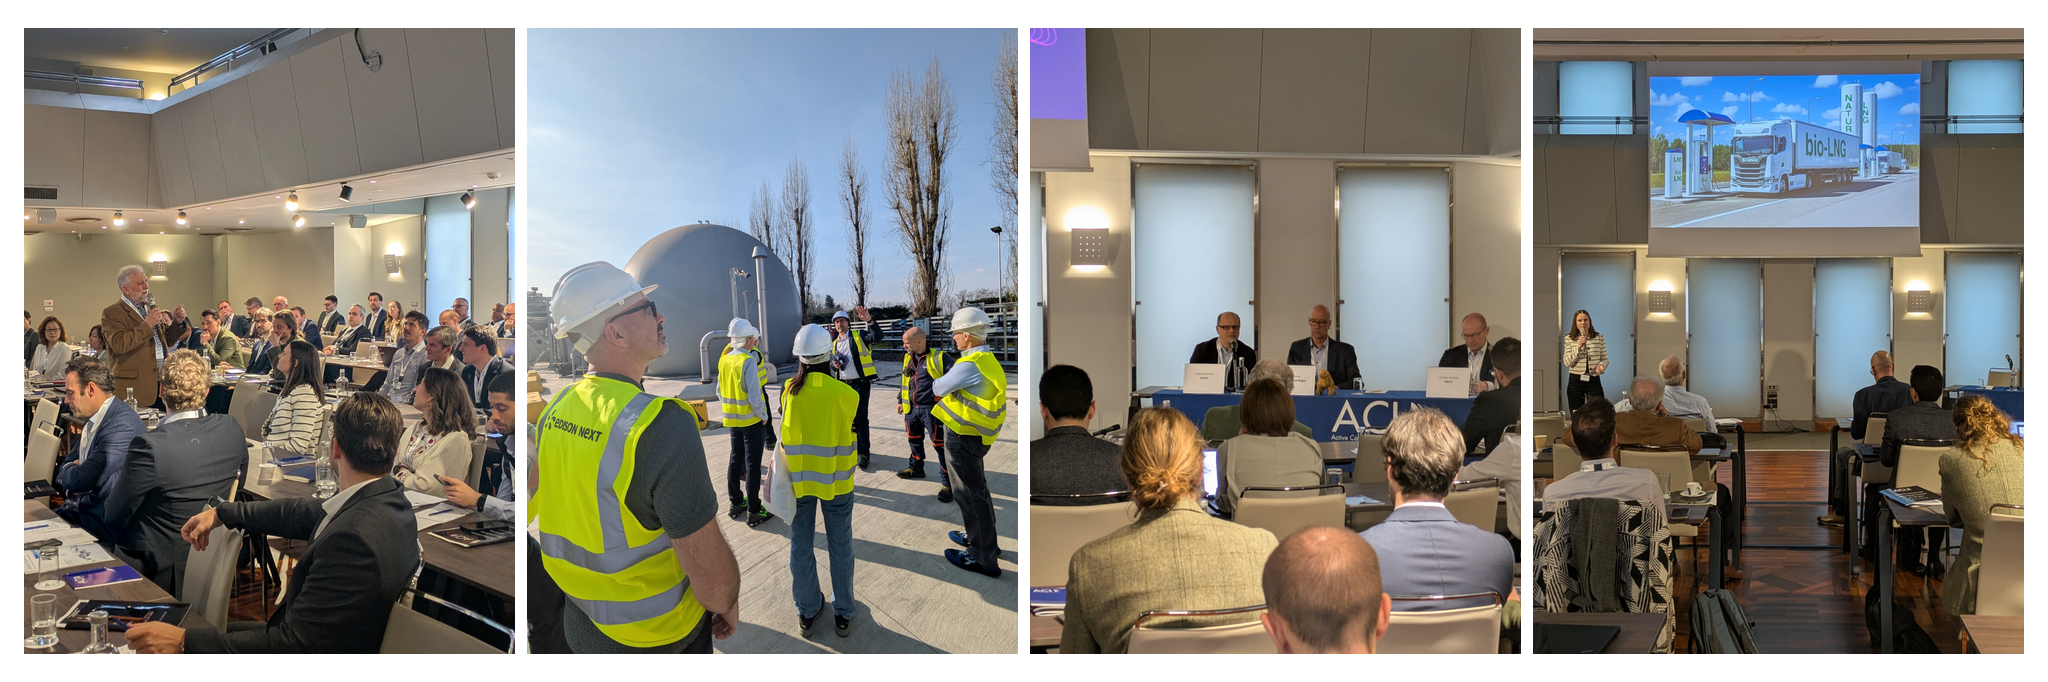
The 2026 edition of ACI’s Future of BioLNG Europe brought together BioLNG and biomethane producers, infrastructure operators, technology providers, investors, certification specialists, shipping and road transport stakeholders, market analysts and industry associations in Turin. Across two days of presentations and panel discussions, the event examined how Europe can move BioLNG from technical potential to commercially credible deployment. The programme connected regulation, project finance, production pathways, cross-border logistics, certification, carbon intensity and end-user demand, with a particular focus on RED III, FuelEU Maritime, investment risk and the practical requirements for scaling supply across road and maritime transport.
Regulation, Certification and Market Access
Regulation was treated as the central force shaping market access, demand and project value. Speakers examined how RED III is being transposed into national legislation, how FuelEU Maritime is influencing renewable fuel economics, and how the EU ETS and evolving IMO framework affect compliance choices for shipping. The discussion showed that more ambitious greenhouse-gas reduction targets and sector-specific obligations can support BioLNG, but different national interpretations, subsidy rules and certificate systems continue to fragment the European market.
Certification and chain-of-custody were therefore discussed as commercial infrastructure rather than administrative detail. Presentations compared Guarantees of Origin with Proofs of Sustainability, explored registry interoperability and considered the role of the Union Database in improving cross-border recognition. Particular attention was given to mass balance and equivalence liquefaction, including how sustainability characteristics are transferred through interconnected gas and LNG systems. Across the event, speakers stressed that credible claims depend on consistent lifecycle accounting, robust audit trails and safeguards against double counting.
Building Bankable BioLNG Projects
Project finance sessions translated market uncertainty into the requirements of lenders and equity investors. BioLNG projects combine substantial capital expenditure across anaerobic digestion, upgrading and liquefaction with a layered revenue model involving feedstock, gate fees, biomethane sales and renewable fuel premiums. To secure funding, developers were advised to demonstrate long-term feedstock availability, creditworthy offtake, proven technology, reliable EPC and operational arrangements, realistic production assumptions and financial models tested against price and policy change.
The programme also highlighted the importance of choosing an appropriate funding structure. Senior debt, strategic equity, asset finance and public funding can each play a role, but none removes the need for strong contractual foundations and transparent governance. Speakers repeatedly connected bankability to policy visibility beyond 2030: if carbon-intensity rules, eligibility criteria or liquefaction treatment change during a project’s revenue period, offtake values and debt capacity can be weakened. Early engagement with funders and conservative modelling were presented as practical ways to reduce this exposure.
Production Pathways, Infrastructure and Cross-Border Supply
Infrastructure discussions showed how existing gas grids and LNG terminals can connect distributed biomethane production with concentrated transport demand. Presentations examined three principal routes: liquefaction at the production site, grid-connected liquefaction and equivalence liquefaction at an LNG terminal. Terminal-based models can draw on established storage, loading and bunkering assets, while transmission and underground storage help balance geographically dispersed production against variable demand. Intermodal transport by truck, rail and vessel was also considered as a route to wider market reach and more flexible logistics.
The development of Zeebrugge was used to illustrate how infrastructure can evolve with the market. Small-scale ship loading, truck-loading capacity, grid-based biomethane liquefaction and a newer equivalence service have progressively opened the terminal to road and maritime BioLNG demand. At the other end of the scale, decentralised technology was presented as a way to reach small and remote farms that cannot access the gas grid. These examples demonstrated that scale-up will require several complementary production and distribution models rather than a single standard route.
Road Transport and the Competing Fuel Landscape
Road transport sessions assessed BioLNG against HVO, battery-electric vehicles, hydrogen and future synthetic fuels. BioLNG was presented as a practical option for long-haul operations where high energy density, vehicle range and established LNG logistics remain important. Existing vehicle platforms and refuelling networks can support near-term emissions reductions, while long fleet replacement cycles make stable fuel availability and long-term supply agreements essential to operator confidence.
Speakers nevertheless rejected a single-fuel view of transport decarbonisation. Duty cycles, payload, infrastructure, regional incentives, total cost of ownership and feedstock availability all influence the appropriate solution. HVO offers drop-in compatibility in many diesel fleets, electrification is expected to expand where operationally suitable, and hydrogen and e-fuels may gain importance as production scales. BioLNG’s role will therefore depend on verified carbon performance, competitive pricing and the ability of producers, vehicle manufacturers and fleet operators to coordinate investment.
Maritime Demand, Green Corridors and Carbon Management
Maritime transport emerged as BioLNG’s strongest long-term growth market. FuelEU Maritime and the EU ETS are creating a clearer compliance value for lower-carbon fuels, while BioLNG can be used in existing LNG vessels and bunkering infrastructure without a wholesale change in propulsion technology. Presentations highlighted early use on European ferry routes and green shipping corridors, alongside growing terminal demand. Market analysis suggested that shipping could take an increasing share of biomethane as road transport gradually faces stronger competition from electrification.
The conference also addressed the limits of fuel substitution alone. Feedstock constraints, competition between end-use sectors, methane slip, residual emissions and variable willingness to pay mean that BioLNG cannot solve every maritime decarbonisation challenge by itself. Onboard carbon capture, CO2 liquefaction, intermediate aggregation, geological storage and carbon utilisation were explored as complementary pathways. Combining BioLNG with carbon capture was presented as a realistic medium-term route to deeper emissions reduction, lower carbon-cost exposure and potential new value from recovered biogenic CO2.
A Practical Industry Discussion
Overall, the 2026 Future of BioLNG Europe reflected a market moving from ambition toward execution. Across finance, regulation, infrastructure, production and end use, the same requirements repeatedly surfaced: credible lifecycle data, stable policy signals, long-term feedstock and offtake arrangements, trusted certification, appropriate infrastructure and closer cooperation between producers and customers. The event showed that BioLNG already has viable applications and scalable routes to market, particularly in heavy transport and shipping, but growth will depend on aligning physical supply, environmental integrity and commercial value across Europe’s fragmented national systems.
ACI has put together a range of packages to suit your requirements. These range from branding options, to full scale partner solutions and can be tailored to meet your objectives and budgets.
If you are launching a new product or service and wish to gain visibility and brand recognition within your industry, contact us today!
For commercial opportunities, please contact:
Anne Bradwell
Tel: +44 20 3141 0623
Email: [email protected]
At the event we strive not only to bring you to the same location at the same time as your customers/suppliers/peers, we strive to ensure you meet face-to-face with each and every one of your target contacts and to provide you with the time you need to have multiple unhurried conversations with them and build a lasting business relationship:
• A pre-event informal introduction the evening before the conference
• A minimum of five hours’ networking built into the two day conference agenda
• A networking grid which enables you to make your target contacts aware you are looking for them
• The option to join either social drinks or dinner during the evening of Day One
• ACI’s on-site team will assist you in locating your hard-to-find target contacts & make face-to-face introductions
Of course, if there is anybody you are unable to meet over the two days, ACI’s event team will do their best to initiate contact after the event.